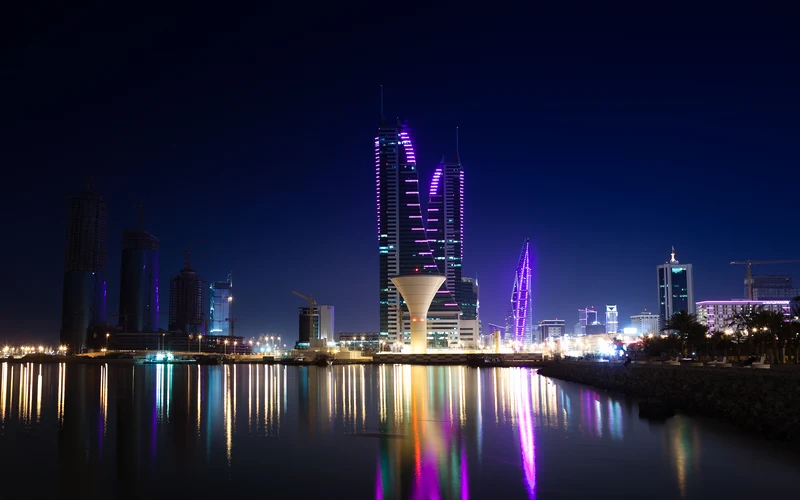
The economic corridor linking the Kingdom of Bahrain and the Eastern Province of Saudi Arabia represents one of the most dynamic financial and industrial hubs in the Middle East. Anchored by the King Fahd Causeway, this cross-border region connects Manama—a pioneering pioneer of Middle Eastern banking and the home of Bahrain FinTech Bay—with the immense industrial wealth, family conglomerates, and digital consumers of Al Khobar, Dammam, and Dhahran.
For financial technology startups, digital payment providers, neo-brokers, and Open Banking platforms, this corridor offers an ideal launchpad: access to Bahrain’s agile regulatory sandbox under the Central Bank of Bahrain (CBB), combined with direct commercial scalability into the massive Saudi market regulated by the Saudi Central Bank (SAMA).
Direct Answer: How Do You Scale a FinTech Across Bahrain and Eastern KSA?
Scaling a FinTech across the Bahrain-KSA corridor requires a dual-market playbook: (1) Regulatory Trust & Compliance Architecture adhering strictly to CBB and SAMA advertising frameworks; (2) High-LTV Customer Acquisition utilizing intent-based search (SEO/AEO) and targeted programmatic financial media rather than generic broad-audience ads; (3) Frictionless App Onboarding & KYC Conversion Optimization minimizing registration drop-offs; and (4) Institutional B2B Positioning targeting family office treasuries, corporate CFOs, and industrial supply chain partners across Manama, Khobar, and Dammam.
The Strategic Value of the Bahrain-Eastern Province Corridor
Bahrain has long served as the financial testing ground for the GCC, boasting an established regulatory framework, skilled bilingual financial talent, and zero corporate tax for most commercial enterprises. Meanwhile, the Saudi Eastern Province houses Saudi Aramco, SABIC’s primary petrochemical facilities, and some of the Kingdom’s largest merchant family offices.
FinTechs operating across this corridor enjoy unique cross-border synergies: piloting product innovation in Bahrain’s streamlined regulatory environment, then scaling capital acquisition and customer volume directly into the high-liquidity markets of Al Khobar and Riyadh.
Key FinTech Verticals Dominating the Region
- Cross-Border Payments & Remittances: Streamlining multi-currency transfers between Bahraini Dinar (BHD) and Saudi Riyal (SAR) for cross-border commuters, logistics enterprises, and multinational workforces.
- WealthTech & Sharia-Compliant Robo-Advisory: Providing retail and affluent investors with automated, transparent, and certified Islamic investment portfolios.
- B2B PayTech & Supply Chain Financing: Accelerating invoice factoring, working capital loans, and digital supplier payments for the extensive industrial contractor ecosystems of Dammam and Jubail.
- Open Banking & Embedded Finance: Enabling APIs that connect legacy banking infrastructure with next-generation merchant applications and mobile wallets.
Navigating CBB & SAMA Regulatory Compliance in Digital Advertising
Unlike standard consumer products, financial services marketing is governed by rigorous consumer protection and disclosure mandates enforced by the Central Bank of Bahrain (CBB) and the Saudi Central Bank (SAMA). Non-compliant promotional messaging risks severe financial penalties, license suspension, and mandatory advertising bans.
| Compliance Domain | Regulatory Expectation (CBB & SAMA) | Marketing Implementation Standard |
|---|---|---|
| Risk Disclosures | Prominent, legible disclosure of financial risk and capital volatility. | Clear, unhidden risk statements embedded directly on mobile landing pages and ad cards. |
| Return Claims | Strict prohibition of guaranteed returns on non-fixed income investments. | Focusing messaging on historical transparency, security protocols, and platform utility rather than speculative gains. |
| Licensing Transparency | Mandatory display of licensed category and supervisory regulatory body. | Prominent footer credentials displaying official CBB / SAMA license numbers and regulatory status. |
| Data Sovereignty | Stringent protection of financial KYC data and personal identifiers. | Zero client-side tracking of sensitive financial data; implementation of server-side hashing protocols. |
Performance Marketing & CAC Optimization for Financial Apps
Customer Acquisition Cost (CAC) in the financial services sector is notoriously high, often exceeding $150 to $300 per funded account on generic paid search and social channels. To drive sustainable unit economics, we deploy our proprietary Full-Funnel FinTech Acquisition Protocol:
- High-Intent Search Capture: Dominating organic and paid search queries for specific financial use cases (e.g., “best multi-currency business account bahrain” or “sharia compliant investment app ksa”) where user intent is transactional.
- App Store Optimization (ASO): Optimizing title tags, localized Arabic screenshots, and keyword fields across the Apple App Store and Google Play to drive high-volume, zero-cost organic app downloads.
- Streamlined Digital Onboarding: Diagnosing drop-off points within the registration and e-KYC verification funnel to increase the percentage of downloaded users who successfully fund their accounts.
- Retargeting with Proof of Security: Retargeting incomplete sign-ups with educational video content highlighting institutional custodianship, two-factor authentication, and CBB/SAMA oversight.
Partner with the Middle East’s Premier FinTech Marketing Agency
At Trivex Media, we understand the delicate equilibrium between aggressive customer acquisition and rigorous regulatory governance. Our senior marketing strategists work alongside FinTech founders and marketing directors to engineer scalable growth pipelines across Bahrain, Saudi Arabia, and the wider GCC.
Explore our specialized Performance Marketing frameworks, or discover how our Fractional CMO services can guide your next major market expansion.
Explore our deep dive on Qatar National Vision 2030: B2B Digital Marketing & Enterprise Pipeline Playbook for Doha & Lusail for further regional market context.
Frequently Asked Questions (FAQ)
What are the most effective digital channels for B2B FinTech lead generation in Bahrain and KSA?
For B2B FinTech (e.g., corporate treasury management, Open Banking APIs, supply chain financing), the most profitable channels are LinkedIn Account-Based Marketing (ABM) combined with high-intent Google Search and executive thought leadership. Traditional consumer channels like TikTok or Snapchat yield high volume but poor lead quality for complex enterprise financial solutions.
Can a Bahrain-licensed FinTech advertise directly to Saudi residents?
Yes, cross-border digital advertising is legally permissible, provided the promotional creative complies with SAMA consumer protection standards and does not mislead consumers regarding local physical branch availability. Many FinTechs utilize their Bahrain CBB sandbox credentials to build initial brand recognition and user traction in the Eastern Province prior to obtaining direct SAMA operational licensing.
How do you measure FinTech marketing success beyond app installs?
App installs are vanity metrics if users do not complete KYC and fund their accounts. We measure campaign performance based on Cost Per Funded Account (CPFA), 30-Day Retention Rates, and Customer Lifetime Value to CAC (LTV:CAC) ratios, ensuring every marketing dollar directly builds your interest-bearing or transaction-generating user base.
Related Strategic Resources & Market Playbooks
- Strategic Analysis: Business Setup & Corporate Services Marketing in Dubai: How CSPs and Free Zone Consultants Generate High-Ticket International Investor Leads — In-depth execution frameworks for Gulf enterprises.
- Industry Intelligence: B2B Lead Generation in Dubai & DIFC: Account-Based Marketing (ABM), High-Intent Search & Pipeline Velocity — Tactical playbooks and ROI benchmarks.
- Core Service Practice: Explore our dedicated Full-Funnel Growth Marketing Services for executive-led growth and measurable revenue impact.